If you are importing goods into Indonesia, you have two ways to bring your shipment into the country. You can clear it at the port under standard customs procedures, or you can move it into a Bonded Zone.
Bonded zones in Indonesia let you bring goods into the country without clearing them through customs straight away. As a result, instead of paying duty, VAT and income tax at the port, you pay when the goods are released for sale in Indonesia.
Below, we walk you through how a Bonded Zone works, available options, and what you need to have in place before you can use one.
What Is a Bonded Zone in Indonesia?
A bonded zone is a customs-supervised facility that Indonesian law treats as sitting outside the country's customs territory, so goods that enter it are not yet considered imported.
For as long as your goods remain inside a bonded zone (Tempat Penimbunan Berikat, or TPB), Indonesian customs applies the following treatment:
- Import duty is suspended.
- Excise is exempted.
- Import taxes (PDRI), meaning VAT and PPh 22, are not collected.
- Import restrictions (Lartas) are not applied on entry, unless the agency responsible for your product requires otherwise.
You pay these only when the goods leave the facility for the Indonesian market, and only on the quantity you release.
Most import permit requirements work the same way, so you can ship first and complete the paperwork while your goods are already in the country. If you end up not selling the goods in Indonesia, you can re-export them without paying any duties or VAT.
Importing Goods With and Without a Bonded Zone
Whether you use a bonded zone or not, your goods pass through the same customs authority and end up paying the same duty and taxes if they are sold in Indonesia. What changes is when you pay and what needs to be in place before your goods can move. To see the difference clearly, it helps to look at both routes step by step.
Importing goods for sale without a bonded zone
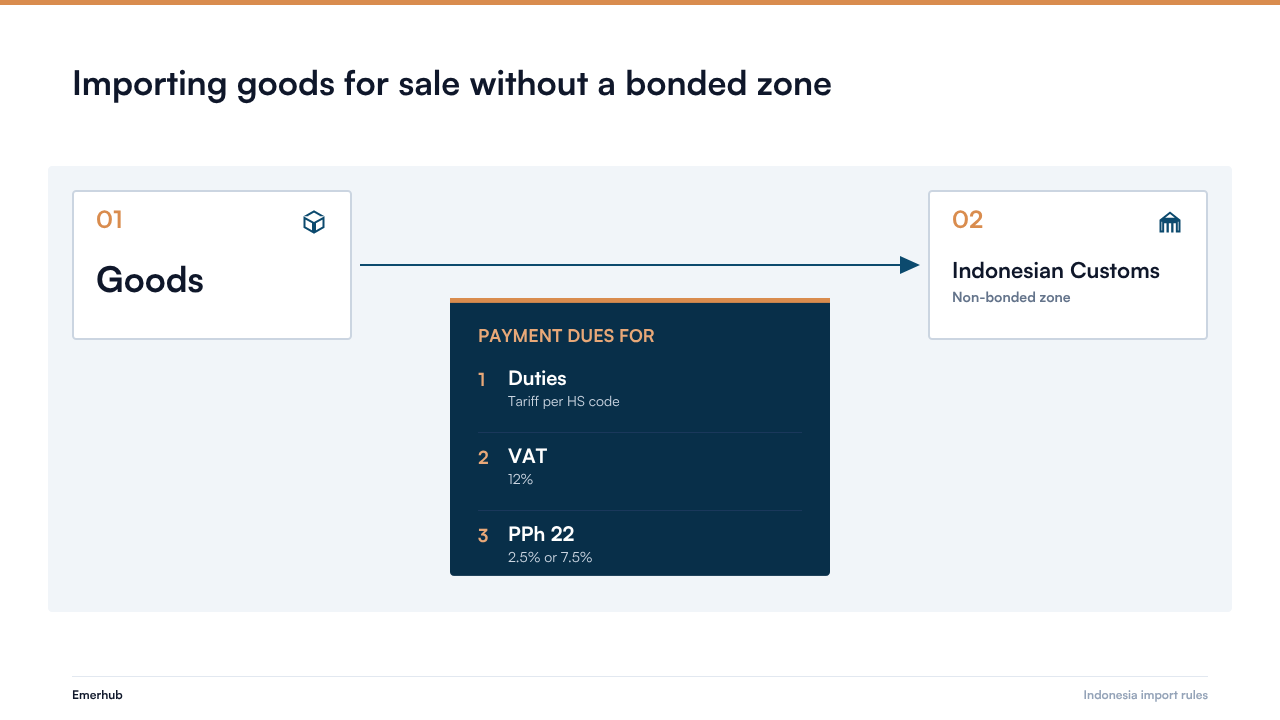
- When your goods arrive at the port, you or your customs broker lodge an import declaration (PIB) with customs.
- Customs then assesses three charges on the shipment. Import duty depends on the HS code of your product. Import VAT (PPN) is 11% for most goods and 12% for luxury goods. Income tax Article 22 (PPh 22) is 2.5% if your NIB carries importer status and 7.5% if it doesn't. Some consumer goods carry a higher PPh 22 rate regardless of your status.
- At the same time, customs checks whether your product needs an import permit. For instance, if your goods require SNI certification, BPOM registration, an Izin Edar or a Persetujuan Impor and you don't have it yet, the shipment will be held at the port until you do.
- Once you have paid all three charges in full, customs issues the release order and your goods can move to your own warehouse.
Keep in mind that VAT and PPh 22 are calculated on the import value plus duty, not on the CIF value alone. In other words, duty raises the base for the other two charges.
Importing goods through a bonded zone
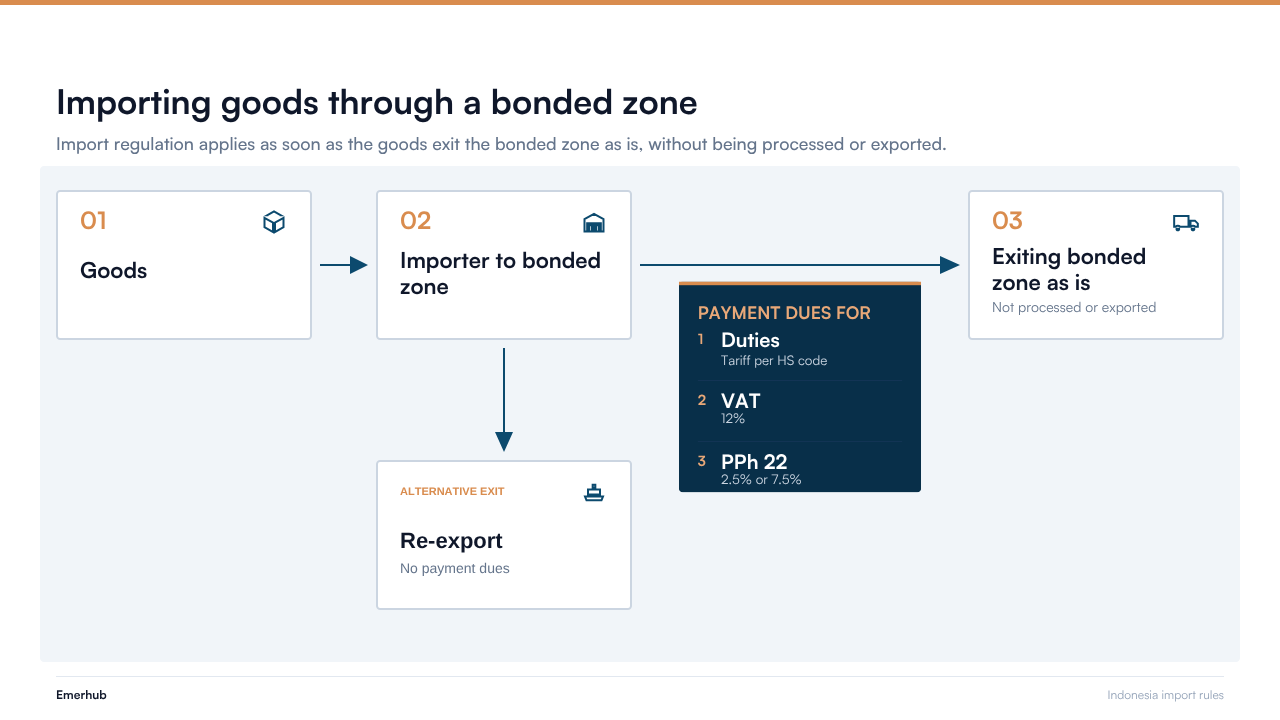
- When your goods arrive at the port, you lodge an entry declaration for a bonded zone (BC 2.3) instead of a PIB.
- Customs suspends duty, exempts excise, does not collect VAT or PPh 22, and does not apply import restrictions. Nothing is paid, and the shipment is not held for missing permits. Prohibited goods, on the other hand, are barred here just as they are at the port.
- The goods then move under customs seal to the facility, where you can store them up to the limit for that facility type: three years in a Bonded Logistics Center (PLB), two in a Bonded Warehouse (Gudang Berikat).
- If you sell them in Indonesia, you lodge a release declaration (BC 2.5) for the lot you are clearing, pay duty, VAT and PPh 22 on that lot, and satisfy any Lartas requirements at that point. If you export them, you lodge an export declaration (BC 3.0) and pay nothing. If you transfer them to another bonded zone, you use a BC 2.7 and the suspension continues.
These procedures were reissued under PER-21/BC/2025, effective 30 March 2026, which updated declaration handling, lane assignment and the treatment of goods subject to Lartas.
Bonded Zone for Final Goods
If you import finished goods to sell in Indonesia, you will use one of the two storage-type facilities: a Bonded Logistics Center (PLB) or a Bonded Warehouse.
A typical case is a distributor that brings in a full container of stock and sells it over six to twelve months, or a brand whose BPOM registration is still in progress when the goods are ready to ship.
Under standard clearance, the first pays the full tax bill on day one for stock it won't sell until much later, and the second cannot ship at all until the permit is issued.
A bonded zone solves both problems.
Storing finished goods in a bonded zone does not reduce your tax bill, however. Every unit you sell in Indonesia will eventually pay full duty and import taxes. The value comes from three other places: timing, permits and flexibility.
1. Cash flow: paying as you sell
Under standard clearance, you pay the full amount of duty and import taxes before you receive your goods. For instance, if you import USD 1 million of inventory at a 10% tariff, your payment at the port looks like this:
| Charge | Basis | Amount |
|---|---|---|
| Import duty | 10% of USD 1,000,000 | USD 100,000 |
| Import VAT | 11% of USD 1,100,000 | USD 121,000 |
| PPh 22 | 2.5% of USD 1,100,000 | USD 27,500 |
| Total before cargo release | USD 248,500 |
Through a PLB, you can instead clear stock as orders come in. If you release 10% of the inventory each month, you pay USD 24,850 per month over 10 months rather than USD 248,500 up front. The total is the same in the end. The difference is that USD 223,650 stays in your business in month one, and you fund the later installments from sales.
Note that VAT and PPh 22 are creditable either way. What you gain is working capital, not a lower tax bill.
2. Permits: shipping before Lartas is complete
Many products need an import permit before you can bring them into Indonesia. Depending on the product, this may be SNI certification, BPOM registration, an Izin Edar from the Ministry of Health for medical devices, or a Persetujuan Impor from the Ministry of Trade.
Under standard clearance, you must have these in hand before the shipment arrives, and some of them take months to obtain.
Inside a bonded zone, import restrictions are not applied on entry unless the agency responsible for your product specifically requires it. You meet the requirements when the goods are released to the domestic market instead.
A PLB can even host inspections by technical agencies on site, so certification work can happen while your goods are already in Indonesia. In the meantime, you avoid demurrage and storage charges at the port.
Note: While Lartas permit requirements are suspended for temporary storage, the deferral covers restrictions (pembatasan), not prohibitions (larangan). Under Ministry of Trade Regulation No. 47/2025, in force since 1 January 2026, goods on the prohibited-import list cannot enter a bonded zone at all. The list includes sugar, rice, hazardous waste, used goods and cooling equipment using HCFC-123.
3. Flexibility: re-exporting unsold stock
Because goods in a bonded zone are treated as outside Indonesian customs territory, you can re-export them without paying Indonesian duty or VAT. This is useful if demand falls, a buyer cancels, or you decide to serve another market from the same stock.
Under standard clearance, you don't have this option. Duty you have already paid is generally not recoverable unless a drawback facility applies, and you only recover VAT through your VAT return.
Bonded Zone for Non-Final Goods
The real advantage of a bonded zone comes when you import non-final goods, such as raw materials, bulk ingredients or unassembled components, for local processing and assembly. Your inputs enter a Kawasan Berikat, the manufacturing type of bonded zone, without duty or import taxes. When a finished product manufactured inside the zone is released into the Indonesian market, customs can calculate duty on the original value of the imported raw materials rather than on the value of the finished product.
For instance, a company that assembles appliances in Indonesia from imported components pays duty on the components, not on the assembled unit. Local labor, packaging, overhead and margin stay out of the duty calculation.
Please note that the raw-material treatment is not automatic and depends on your product and your facility's license setup. It is advisable to consult our local experts before you build your cost model around it.
Limit on domestic sales
A Kawasan Berikat is designed for export manufacturing, so there is a limit on how much you can sell in Indonesia.
Under current regulations, domestic sales are capped at 50% of what you exported the previous year.
If you exported USD 1 million last year, for instance, you can sell up to USD 500,000 into the Indonesian market this year. Sales to other bonded zones and free zones count as exports for this purpose.
To sell more than the cap allows, you need approval from the Director General of Customs and Excise, backed by a recommendation from the industry ministry. If most of your sales will be domestic, a Kawasan Berikat license is the wrong fit.
Which Type of Bonded Zone Do You Need?
There are several types of bonded zones in Indonesia, and each one is licensed for a specific purpose. For instance, if you import finished goods to sell, you will need a storage type. On the other hand, if you import raw materials to process, you will need a manufacturing type bonded zone.
Here are three most common types of bonded zones used by importers and foreign companies:
| Bonded Logistics Center (PLB) | Bonded Warehouse (Gudang Berikat) | Manufacturing Zone (Kawasan Berikat) | |
|---|---|---|---|
| Used for | Storing and distributing imported goods | Storing imported goods for a fixed group of buyers | Processing imported materials into finished goods |
| Best suited to | Distributors and brand owners | Suppliers to factories, duty-free shops, transit traders | Export-oriented manufacturers |
| Maximum storage | 3 years | 2 years | Length of the production cycle |
| Sales to the Indonesian market | Yes | Only to the permitted buyer group | Capped at 50% of last year's exports |
Bonded Logistics Center (PLB)
If you import finished goods for sale in Indonesia, the PLB is the type you will most likely use. You can store goods for up to three years, release them in partial lots as you sell, or ship them on to other countries.
A PLB can also hold stock that is still owned by your overseas supplier.
Bonded Warehouse (Gudang Berikat)
A Gudang Berikat serves a fixed group of buyers rather than the open market: factories that need imported materials and parts, duty-free shops, or goods in transit to another country. If you sell consumer goods to the general market, this type does not fit, and a PLB is the usual alternative.
Manufacturing Zone (Kawasan Berikat)
A Kawasan Berikat is a licensed manufacturing site, usually inside an industrial estate. Imported materials and machinery enter without duty or import taxes, and you process them into finished goods for export. Sales into Indonesia are allowed within the limit described above.
Working with Emerhub on Your Import Strategy
As a foreign company, you cannot lodge an import declaration in Indonesia under your own name. You will need either a local entity with import licenses or an Importer of Record. Emerhub can help with both.
If you plan to set up locally, we register your PT PMA and obtain the NIB, customs access and product-specific import licenses you need to contract with a bonded zone operator.
Incase you want to start shipping first, we can act as your Importer of Record and handle the importation and licensing process on your behalf. This is also a good way to test the market before committing to an entity.
Fill out the form below to talk to our local experts in Indonesia, and we will work out which route fits your product and volumes.
Frequently asked questions
Can I ship goods to Indonesia while BPOM or SNI approval is still pending?
If your BPOM or SNI approval is pending, you can still ship your products into a bonded zone in Indonesia. Restrictions are not applied on entry unless the responsible agency requires it, and you release the goods once the permit is issued.
How long can my goods stay in a bonded zone?
Up to three years in a PLB and two years in a Gudang Berikat. Goods in a Kawasan Berikat are tied to the production process rather than a fixed storage period.
Can I use a bonded zone without an Indonesian entity?
Not directly. The import declaration must be lodged by an Indonesian entity with importer status. An Importer of Record can act as consignee on your behalf while you retain ownership of the goods.
What specific taxes are deferred when importing through an Indonesian Bonded Zone?
When importing into a Bonded Zone (Tempat Penimbunan Berikat), import duties, 12% Import Value-Added Tax (VAT/PPN), and Income Tax Article 22 (PPh 22 at 2.5% or 7.5%) are suspended upon entry. These duties and taxes only become due when the goods physically exit the facility for release into the domestic Indonesian market.